
Boring, durable, cash-flowing.
We target essential real estate in the American Midwest, assets whose value comes from the rent check, not the exit multiple. Here's exactly how we source, underwrite, and operate.
Three things have to be true. In our markets, they are.
Demand is steady
Hospitals, plants, distribution centers and farms anchor the towns we buy in. People who work there need a decent place to live and a place to shop nearby, and that does not change with the news cycle.
Supply is thin
Very little gets built in a city of 60,000 people. Most of the apartment stock is older Class B, so a well run building with clean turns stays full and can push rents a little each year.
Pricing is rational
We buy below replacement cost from owners who are ready to move on, in deals too small for the large funds. That is where day one cash yield comes from, before any renovation.
What we buy.
Asset type
30 to 150 units
Workforce multifamily (30 to 150 units) and grocery anchored or necessity based neighborhood retail centers.
Geography
Midwest secondary metros
Secondary and tertiary Midwest metros. Primary markets of interest include Cedar Rapids, Sioux Falls, Rochester, and Des Moines.
Check size
$1M to $5M of equity
$1M to $5M of equity per transaction. Total deal size typically $5M to $20M.
Hold period
5 to 10 years
5 to 10 years. We have no artificial fund life forcing us to sell.
Return profile
Cash yield first
We underwrite for current cash yield from year one, with appreciation treated as a bonus rather than a requirement. Return details for any offering are shared only in its offering documents.
What we avoid
No towers, hotels or office
Class-A urban high-rises. Hotels. Office. Anything that requires a trend to continue for the deal to work.
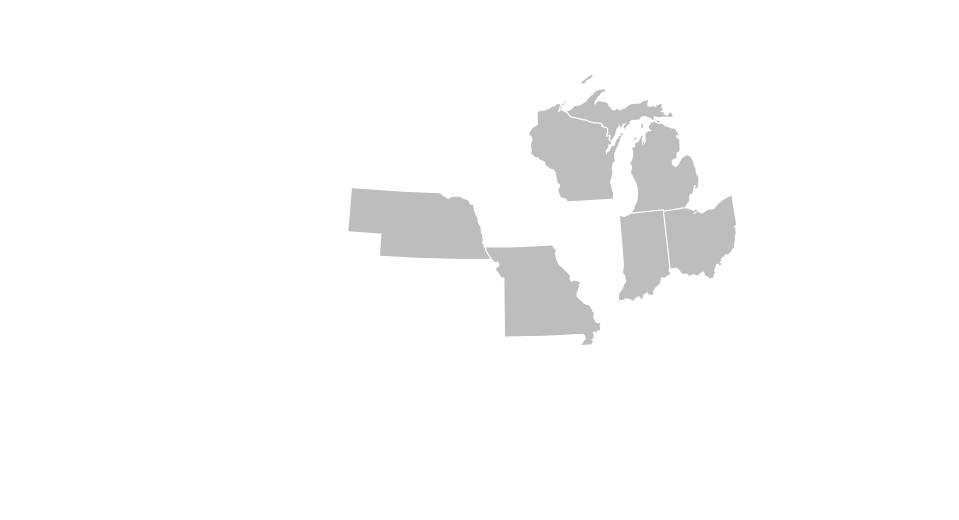
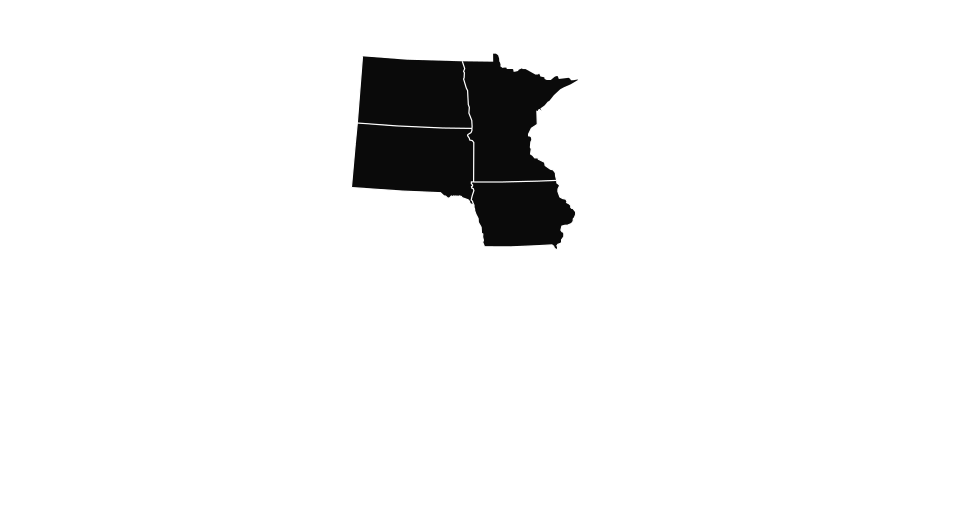
Four core states. Six we underwrite selectively.
Core markets
Iowa, Minnesota, North Dakota and South Dakota are home.
Expansion markets
Indiana, Michigan, Ohio, Wisconsin, Nebraska and Missouri get a look when the numbers and the operator on the ground are right.
From first look to closing.
1
Source
Off-market relationships with regional brokers, operators, and owners. Most of our best deals never hit a listing service.
2
Screen
One-page underwrite in 48 hours. Honest go or no-go based on in-place yield and submarket fundamentals, not a spreadsheet gymnastics exercise.
3
Diligence
On-site walk within a week. Physical inspection, lease audit, market comps, CapEx modeling, and a conservative debt-sizing analysis.
4
Commit
Partners co-invest personal capital in every deal. LP capital is called only after hard money is at risk. No blind pool commitments.
5
Operate
Hands-on asset management. Monthly financials from property managers reviewed line by line. CapEx deployed deliberately, not on a schedule.
6
Realize
Sell when the market pays us for patience, or refinance and keep compounding. We are never forced to transact.
Start wherever you are.
Ready to invest
Review the current offering documents. Access is password protected and limited to accredited investors we already know.
Current offeringsWant to talk first
A short call with a partner about how we buy, operate, and report. No pitch.
Book a callJust getting to know us
Receive our quarterly letter and updates on what we are buying and why.
Join our investor listArka offerings are private placements available only to accredited investors with whom we have an existing relationship. Nothing on this site is an offer to sell any security.